By Maria Josife
AI in marketplaces: what’s working in leadership, what isn‘t and what comes next
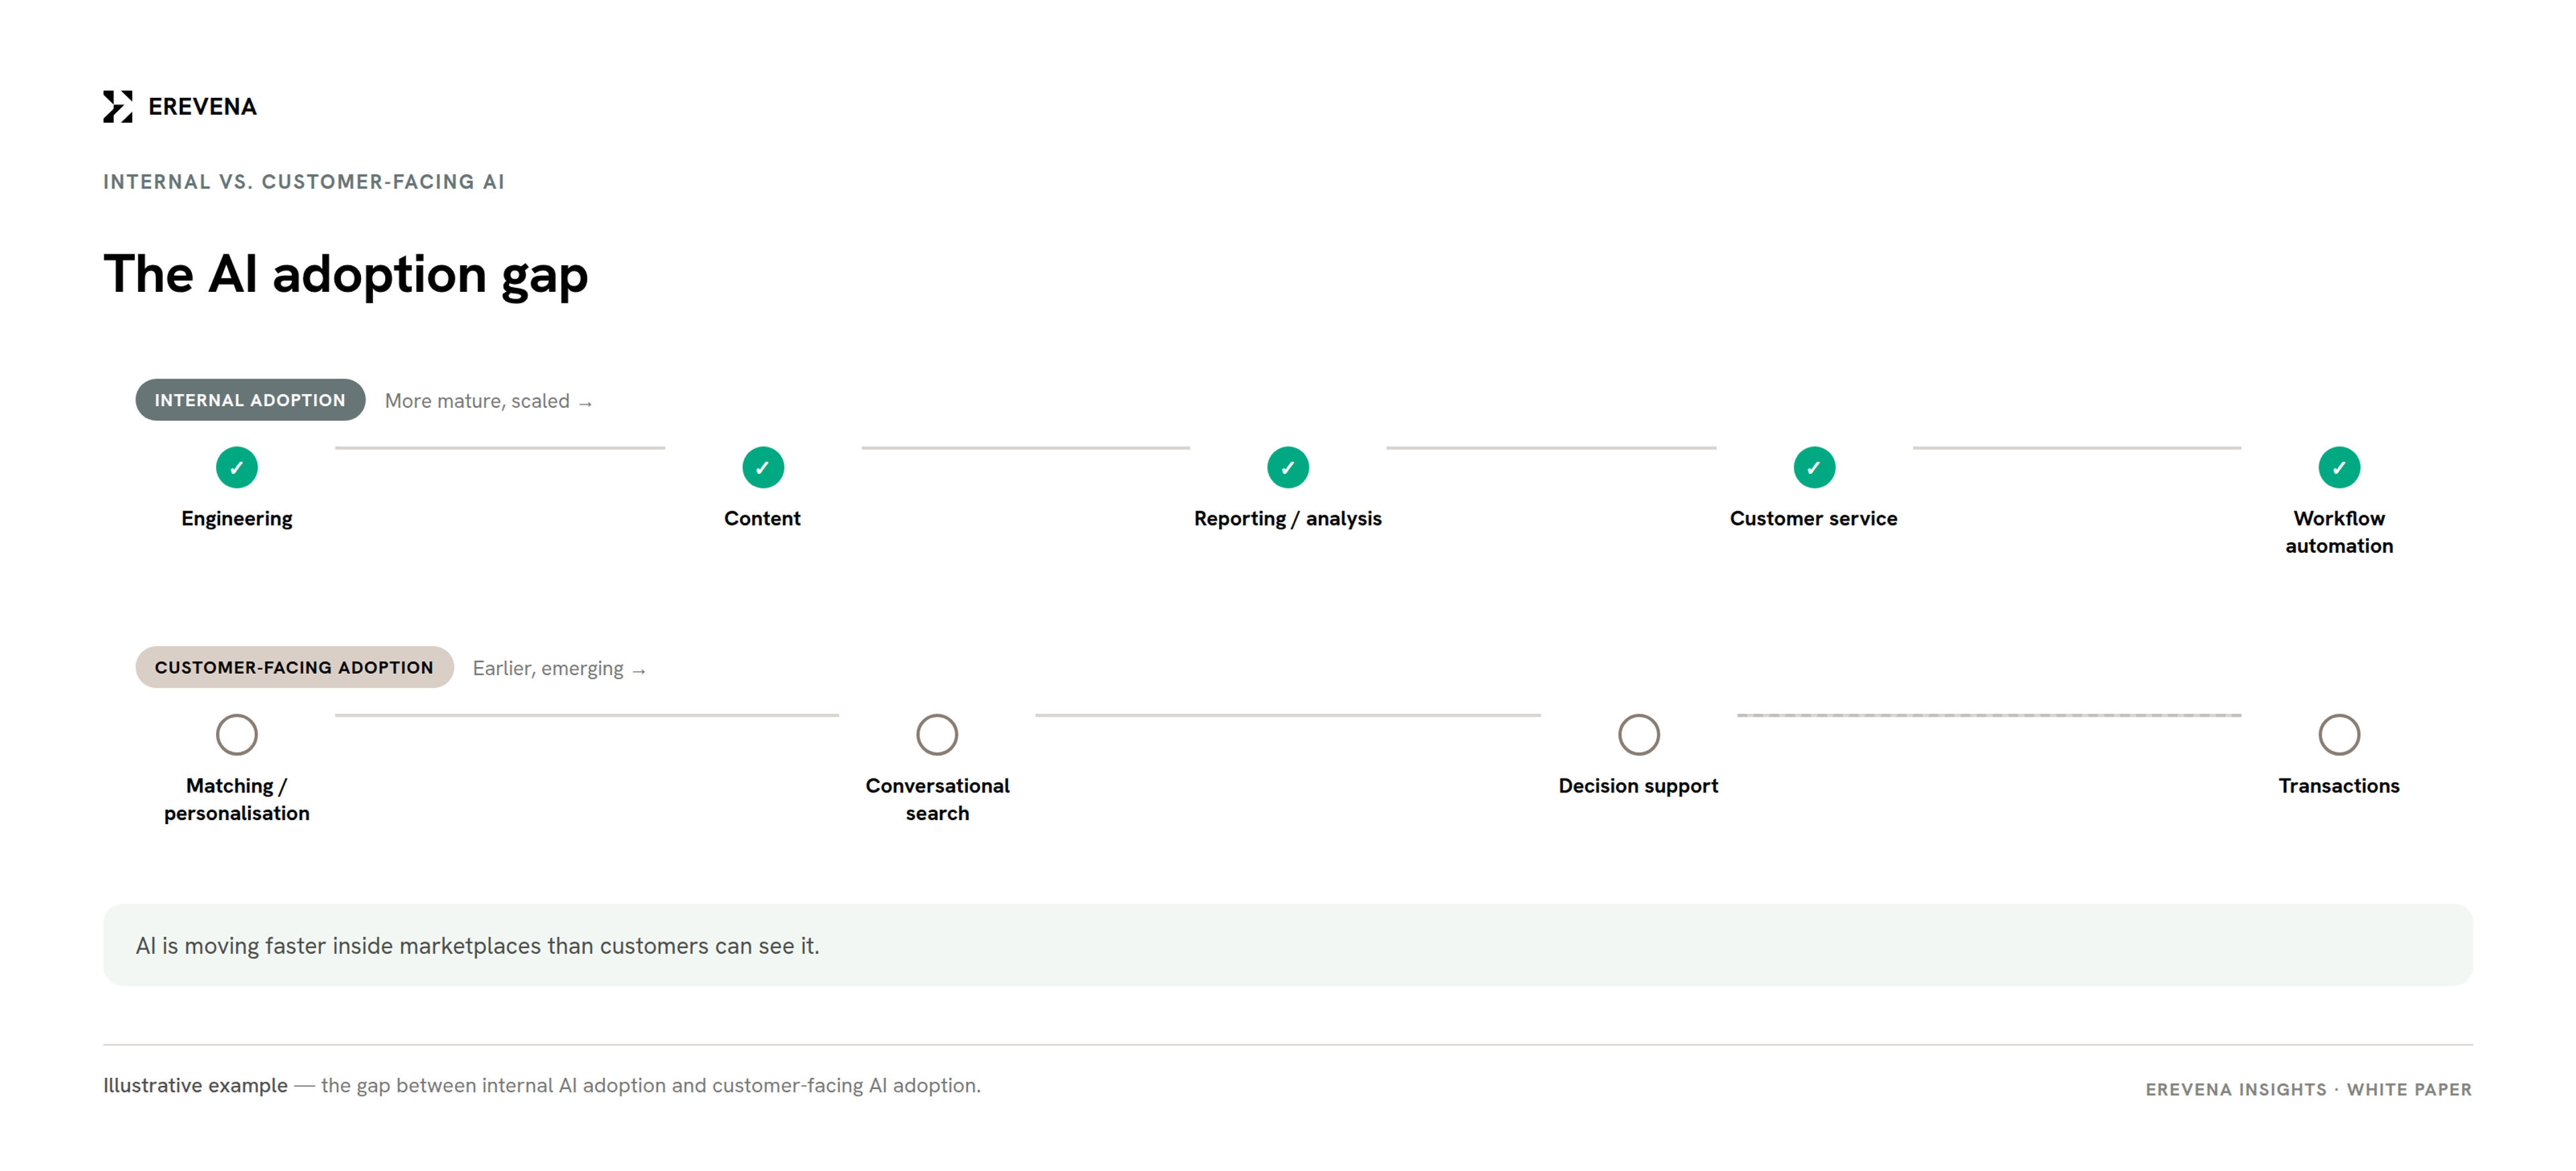
Over the past year, one pattern has come up repeatedly in our confidential conversations with marketplace executives: AI is moving faster inside these businesses than in the products their customers can see, changing how they operate and reshaping their leadership teams. Across the marketplaces we work with, some of the most tangible uses are in engineering, content creation, customer service and workflow automation.
Executives at one confidential major UK marketplace recently told us that their internal AI programme was further ahead than the consumer product they were preparing to launch, and a senior executive at a European travel platform described the logic as efficiency first, growth second. Businesses are using AI to remove cost and effort from expensive processes, then using that capacity to run more campaigns, ship more product, and support growth.
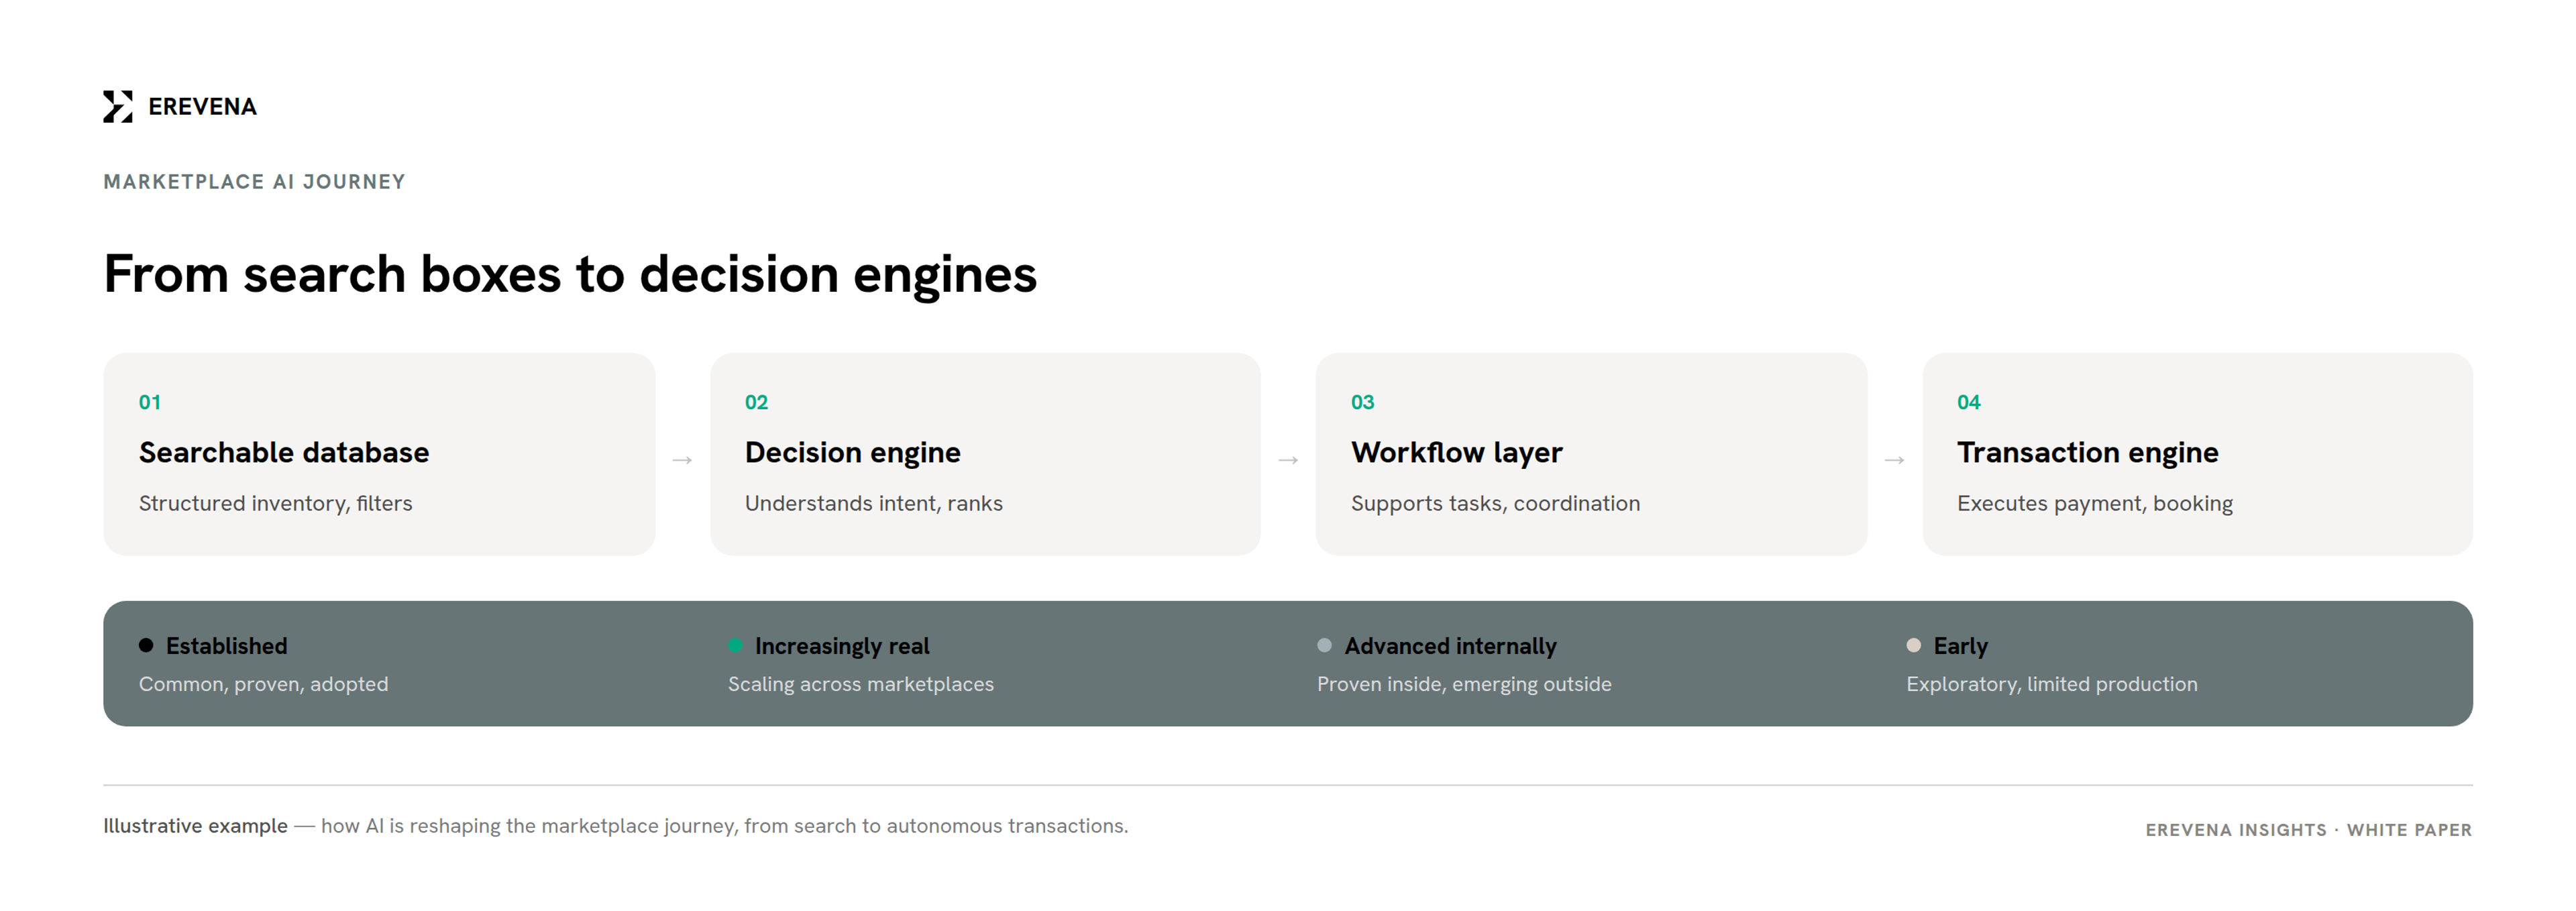
Behind those use cases is a bigger shift. Marketplaces have historically been searchable databases, but AI has created the possibility of moving beyond that model – understanding more of a customer’s intent, helping them decide and, eventually, supporting more of the workflow and transaction around it. Much of that change is starting inside the business before it reaches the customer. The more consequential shift, though, is what this is doing to leadership structures themselves: who owns AI, where functional boundaries now sit, and what boards are starting to expect of a contemporary executive.
Where AI is being applied first and what we’re seeing in leading marketplaces
AI is first being deployed in engineering productivity, content creation, internal analysis, customer-service automation and seller tooling, and this is already in production across many of the marketplaces we work with. We also see common usage in ranking, matching and personalisation, although much of that capability predates generative AI.
Looking at the wider market, Auto Trader is a good example of AI adoption. Its Co-Driver tools generated 2.7 million AI-powered vehicle descriptions and image re-orders in FY26, with 66% of retailers using the product in the previous 30 days.
Our conversations also suggest that productivity is further ahead than monetisation. In a confidential interview we had with one travel platform, the feedback was that AI is expanding capacity in design, marketing and engineering, but its use in pricing and other commercial decisions is much harder to isolate. For now, it is generally easier to show the value of producing more with the same resources than to point to a new AI-driven revenue stream.
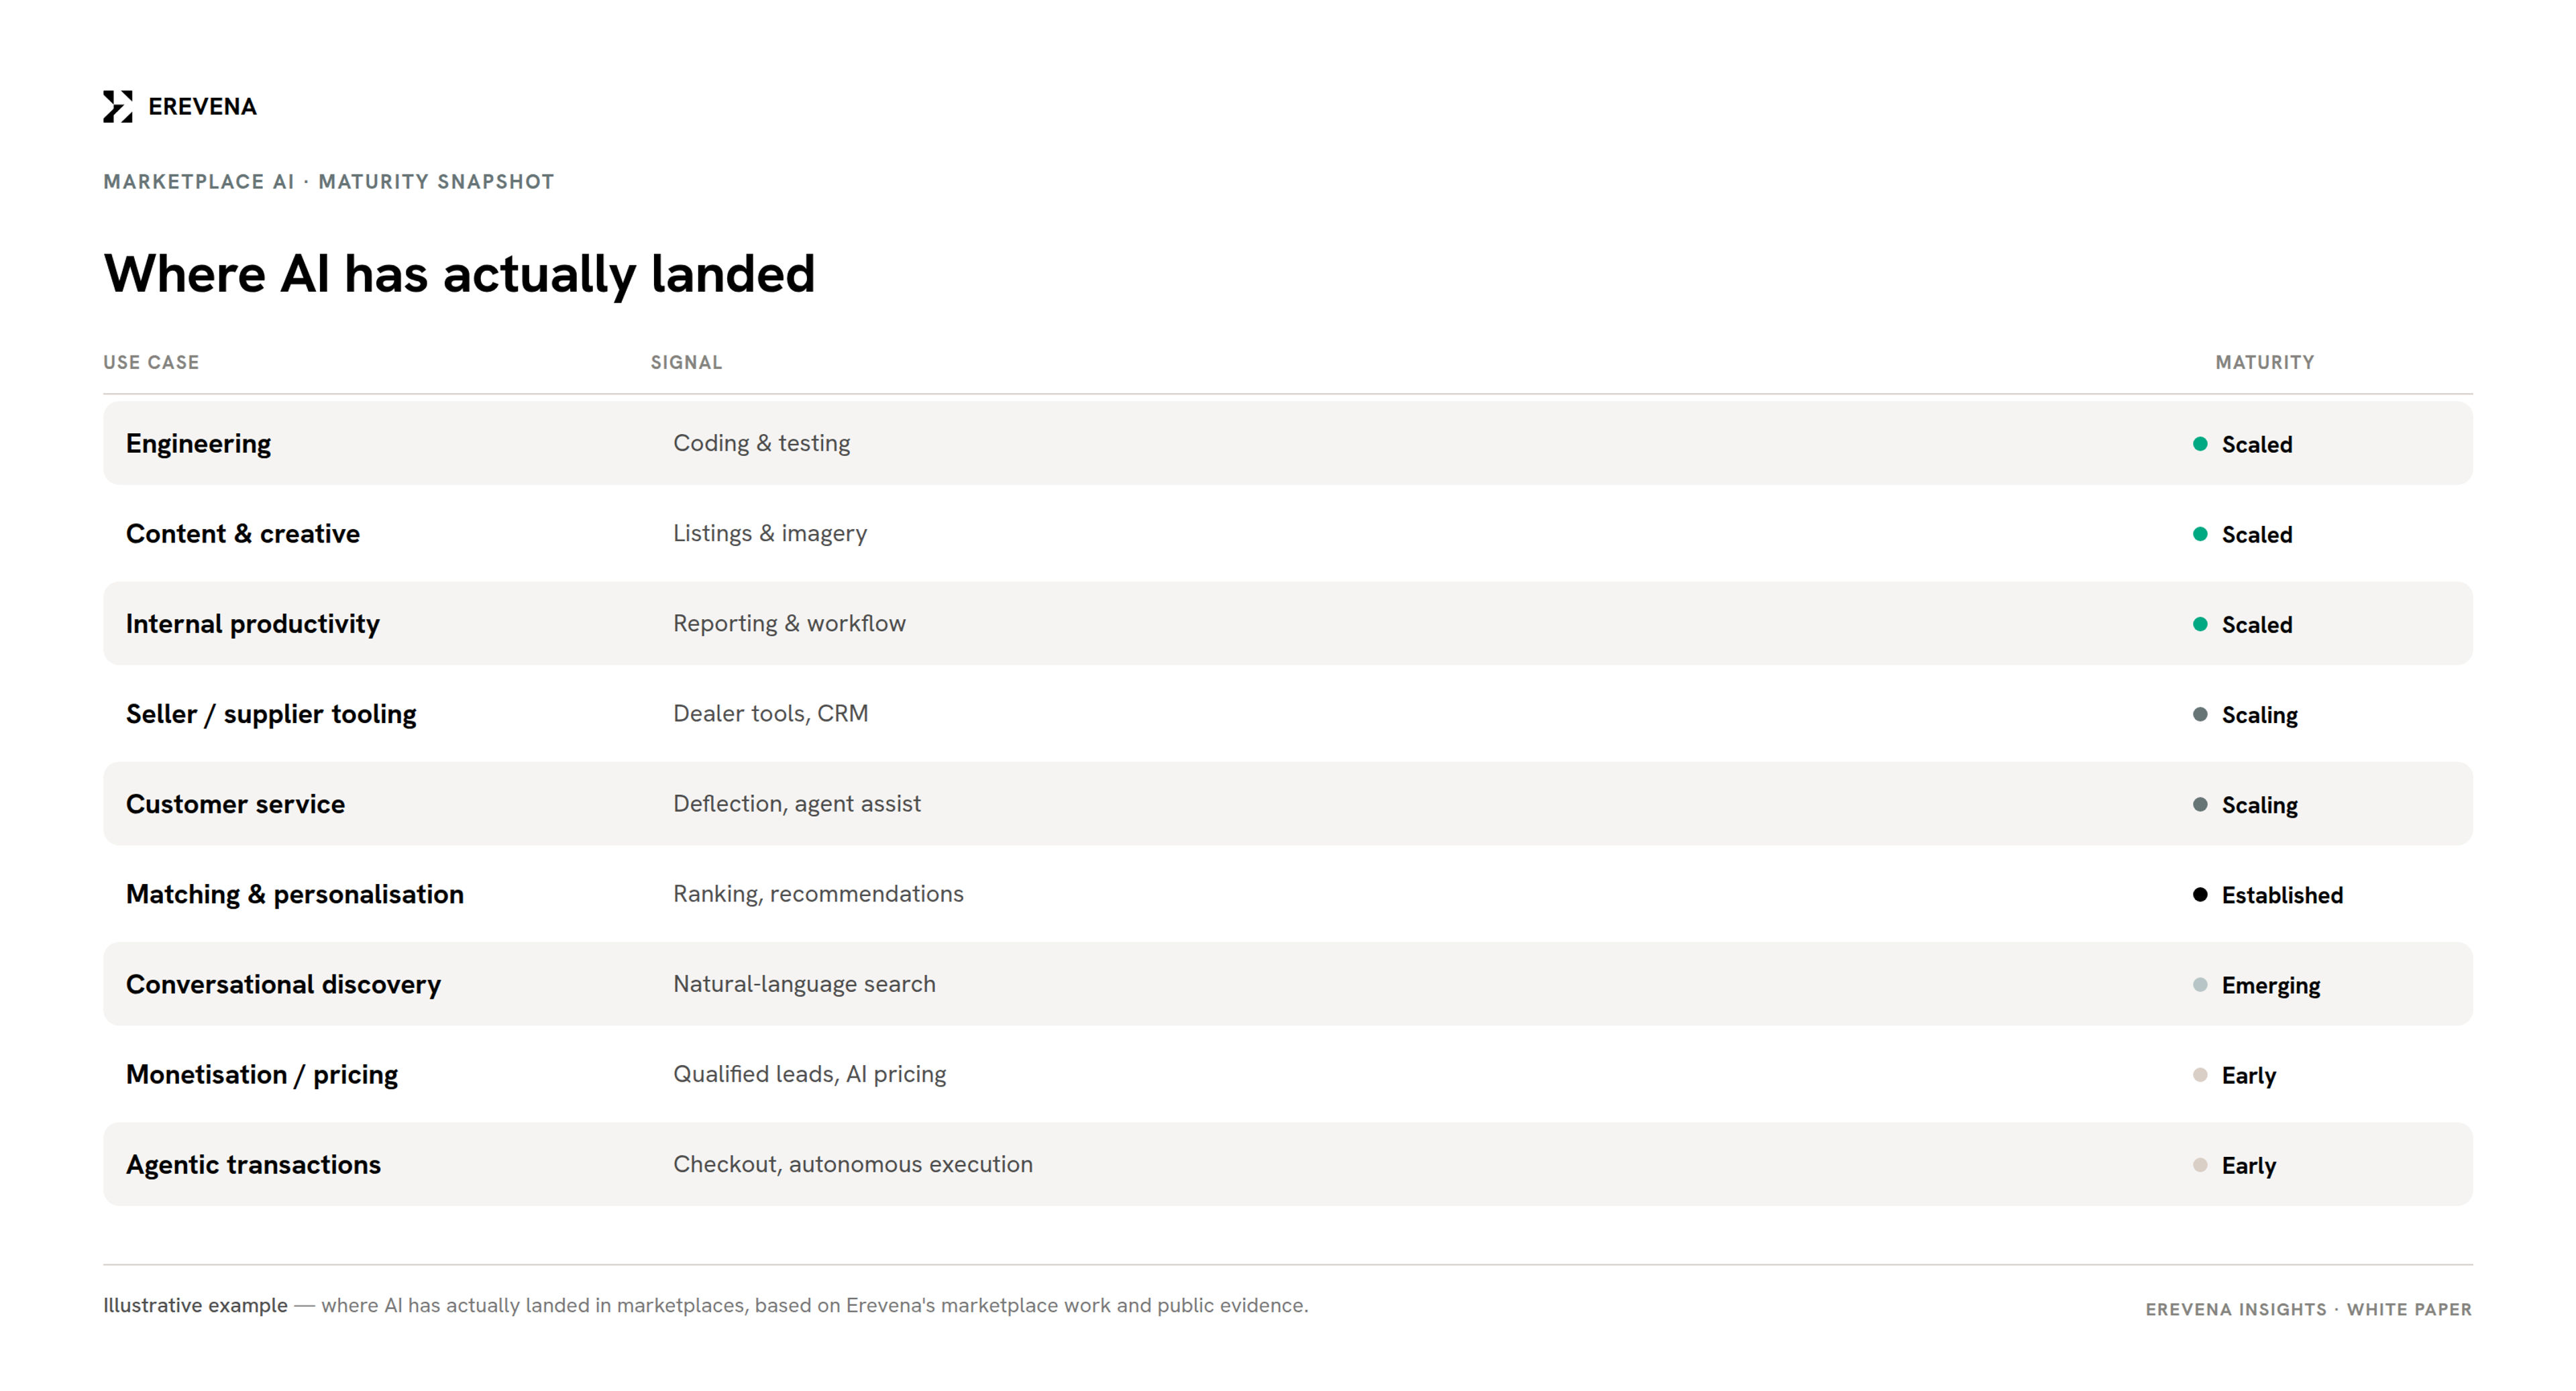
There is a similar pattern on the supply side. Some of the clearest investment we have encountered is aimed at dealers, sellers and suppliers rather than consumers. Improving listing quality, reducing work for sellers or helping them convert more effectively provides a relatively direct route to value; consumer behaviour takes longer to change.
From search and browse to intent-led journeys
Boards are focused on whether AI assistants become a new starting point for categories historically owned by search engines and destination platforms, and we have seen LLM-driven discovery appear in both board mandates and executive searches. Zoopla’s April agreement with OpenAI gives a useful indication of where things are today: AI platforms still represent a small share of property-search traffic, while testing of AI-powered search on its app produced an 80% increase in listing views and a 150% rise in leads. The figures are from testing but suggest AI may change the marketplace experience before it materially changes where users start their search.
Continuing with the Zoopla example, an AI assistant can answer a question such as: ‘average asking prices for a 3-bed flat in Clapham’ on its own. A request for what’s available right now still has to be answered by the marketplace holding the supply. The nearer-term change may therefore be a more fragmented discovery journey, increasing the importance of brand, first-party data, CRM and direct customer relationships.
Conversational interfaces can also tell marketplaces much more about what people want. In one set of experiments discussed with an operator, users volunteered several times more information through conversational search than through conventional filters. Japan’s LIFULL HOME’S took the idea further by inviting consumers to test its property-search AI with unusual requests, including asking for somewhere they could cry after a breakup.
A jobseeker wants the right next move, not a list of jobs; a car buyer wants to know what fits their circumstances; a homebuyer wants context and trade-offs, not simply bedrooms and postcode filters. But richer intent is only useful if the marketplace can retain and act on it. A recurring theme in our conversations is that proprietary data is described as a competitive advantage and an unfinished project almost in the same breath.
This is also changing what marketing leaders are hired and measured on. Erevena CMO Danielle Le Toullec shared: “Marketing fundamentals haven’t changed, but the environment has. AI models evaluate trust the same way good journalists and buyers always have: they look at what others say about a company, not just what it says about itself. For marketplaces, that means visibility now happens before traffic, in the summary layer, before anyone clicks through. Third-party credibility, first-party data and the direct customer relationship are what stop a marketplace disappearing behind the assistant that’s now doing the deciding on the customer’s behalf.”
From decisions to transactions
AI will eventually move from helping customers decide to helping them act, although our conversations suggest this is still very early. Across several hundred executives we have spoken to in payments, identity and fraud, questions around agent identity, authorisation, liability and consent are still rarely part of mainstream discussion.
A June study from Checkout.com gives a similar picture: merchants estimated that only 3% of transactions currently involve AI agents, despite 89% saying they are actively preparing for agentic commerce. Google is already building infrastructure around that possibility through its Universal Commerce Protocol and Universal Cart.
For marketplaces, the question is less whether autonomous checkout and agentic commerce are around the corner and more what happens if the journey becomes increasingly machine-mediated. In automotive, that could connect discovery with finance and payment; in property, affordability and mortgages; in jobs, applications and screening. Payments, identity, permissioning, fraud and customer ownership are becoming product questions as much as infrastructure questions.
How AI is shaping leadership teams
We are seeing several approaches to AI leadership teams and ownership, but relatively little evidence that permanent standalone AI functions are becoming the norm.
Our recent compensation report in collaboration with Ravio identified that candidates with proven AI experience are commanding 15-25% higher base salaries across CTO, CPO and CMO roles, reflecting how quickly demand is outpacing supply.
At one large classifieds group, a central AI team built reusable capabilities and took use cases most of the way towards production before handing them to vertical product teams to finish and run. At a European travel platform, the centre is lighter: a cross-functional steering committee sets priorities and targets, while leaders in product, engineering, marketing and commercial remain accountable for applying AI within their own areas.
Skyscanner is an interesting public exception. It retired the Chief Product Officer title when former CPO Piero Sierra became Chief AI Officer, giving AI a cross-cutting C-suite mandate spanning traveller products, engineering, internal productivity and partnerships. Elsewhere, in marketplaces like OLX, AI ownership has moved in the opposite direction, becoming embedded inside existing product, data or operational teams. Vend has taken another route again, creating an independent AI unit to explore AI-native marketplace experiences while explicitly describing the structure as temporary.
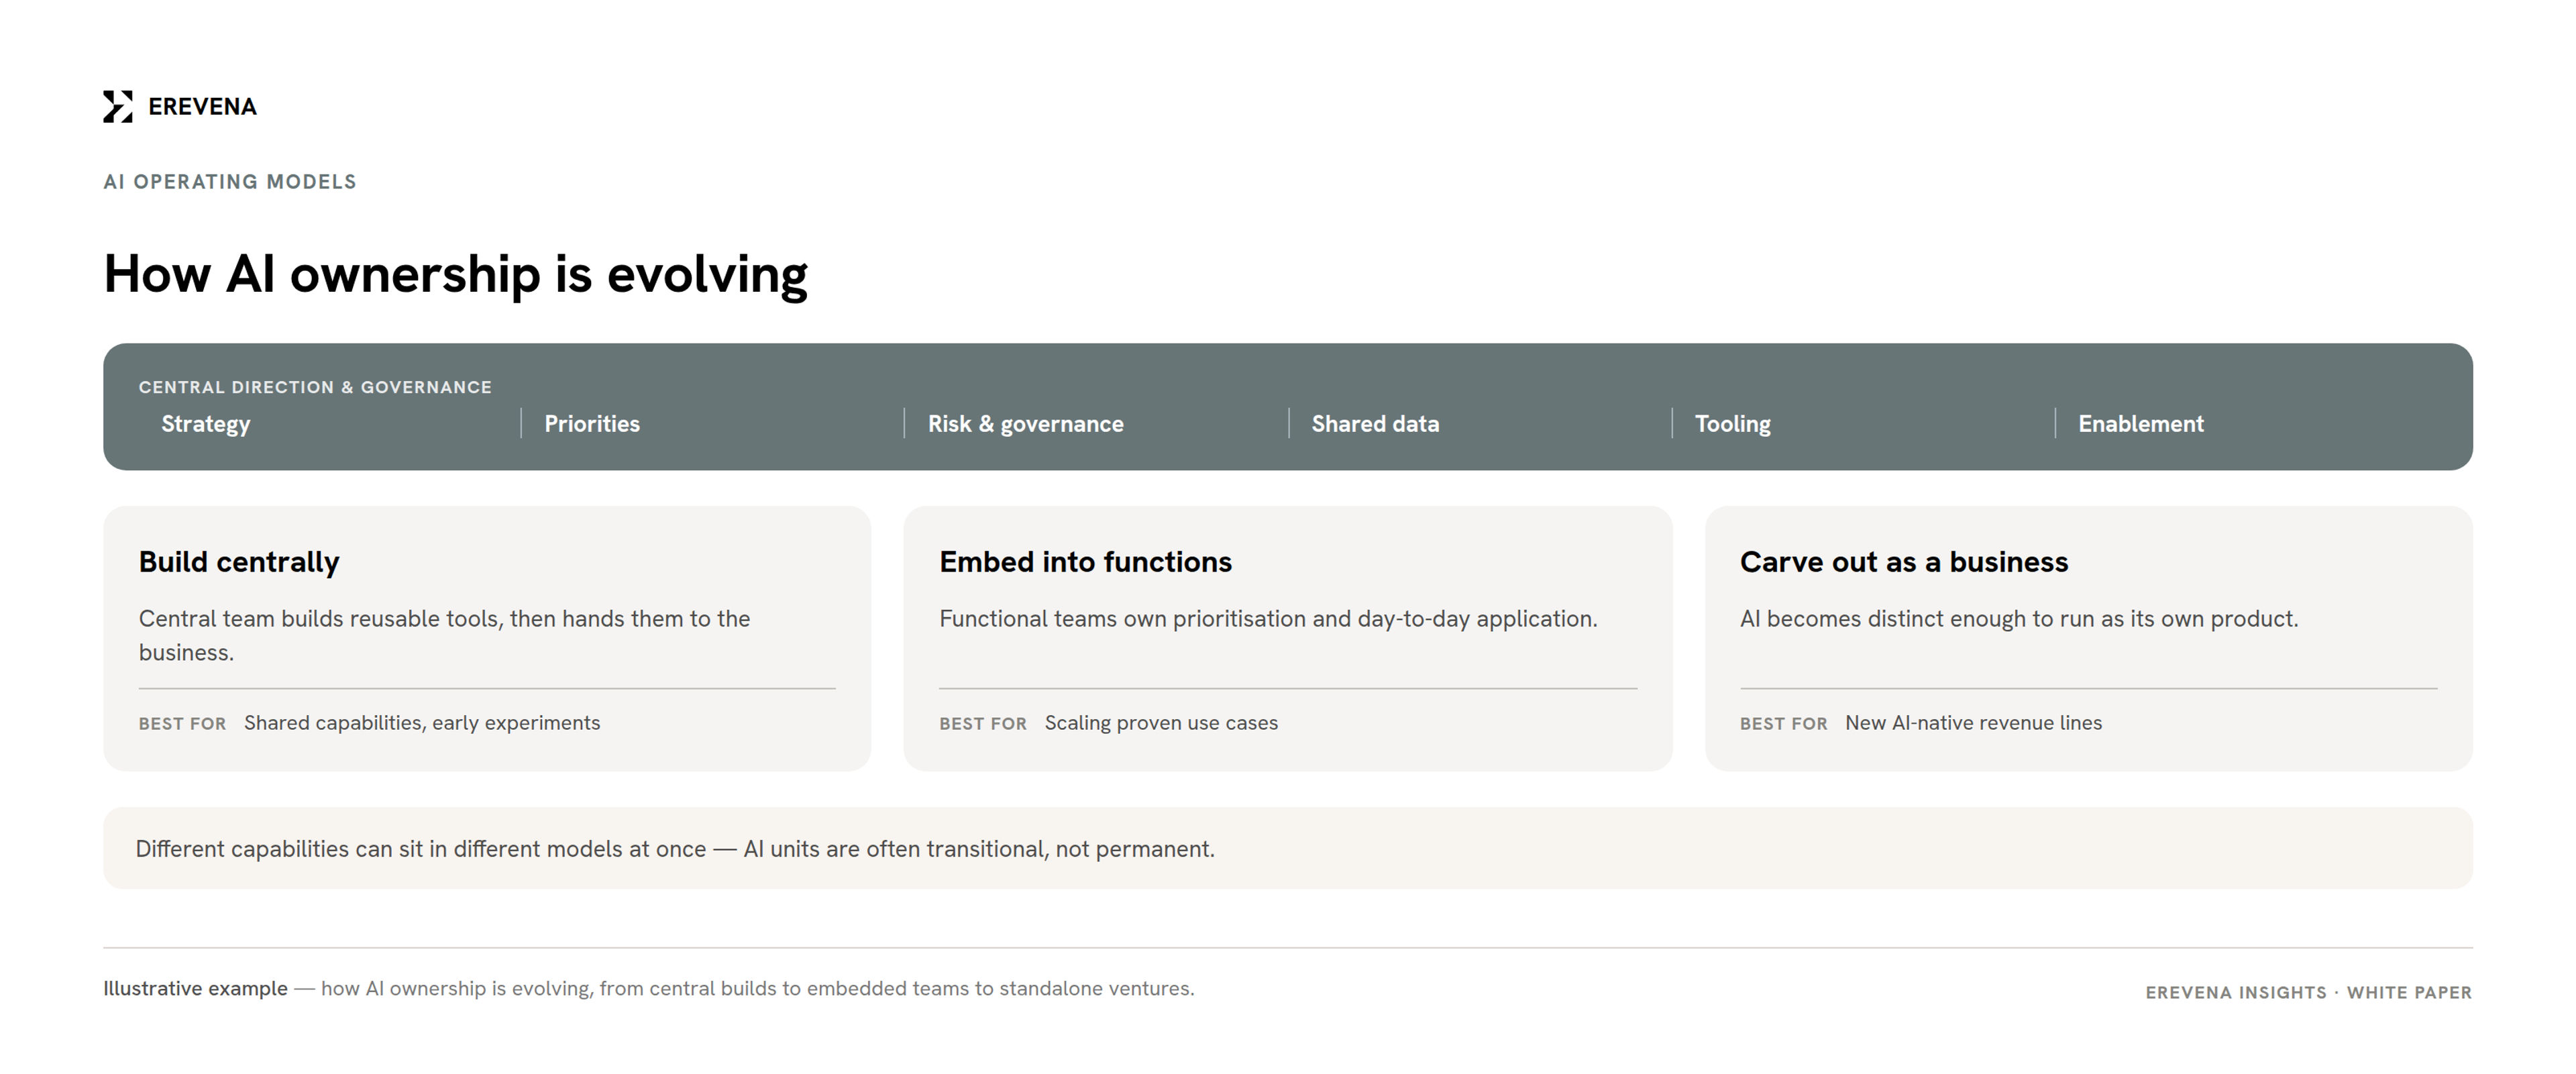
Customer service and operations show why there is unlikely to be one answer. Across the marketplaces we reviewed, AI is reducing contacts, automating workflows and giving service teams better tools – but with varying organisational responses. In one travel marketplace, customer service is moving closer to Product because service issues are increasingly treated as part of the core customer experience; in a resale marketplace, Operations have instead built their own product and engineering capability around automation.
The common thread is that AI ownership is sitting where the underlying problem lies. Shared data foundations, tooling and specialist expertise can sensibly be centralised, but accountability for applying them tends to move back towards the teams closest to the customer, supplier or workflow. In the businesses moving fastest, that distributed execution is usually matched by clear sponsorship from the CEO’s office. The execution may sit within individual functions, but the direction, urgency and permission to rethink established ways of working are being set from the top rather than delegated to a single functional AI owner.
What this means for marketplace leadership
Search visibility increasingly spans marketing, product, data, brand and distribution, while matching involves product, machine learning, commercial strategy and marketplace liquidity. Agent-mediated transactions bring product, technology, finance, risk and partnerships into the same customer journey. Operations is a particularly interesting example. Across the marketplace businesses we reviewed, the traditional standalone COO is becoming less of a default. Skyscanner has not replaced the COO seat since Bryan Batista moved into the CEO role; Vinted operates without a group-level COO; elsewhere customer service is moving towards Product, or Operations have been combined with another function. Rightmove sits at the other end of the spectrum, with product, technology and operations consolidated under a broad COO remit. There is no single organisational answer, and broader remits are not always the solution. Trainline split Product from Growth in 2025, while OLX recently pulled Marketing back out of a wider product, data and technology structure.
The shift is in what businesses see as expected of a contemporary executive, rather than as specialist expertise. In one recent marketplace CMO search, AI fluency sat within a cultural assessment rather than as a test of functional experience. Increasingly, we would add comfort with ambiguity and first-principles thinking to that baseline: leaders are being asked to make decisions where the technology, operating model and even the boundaries of their role are still moving. They need to understand how changes in their own function affect adjacent parts of the customer journey – without necessarily owning all of them. We are seeing the same shift at board level, with growing demand for NEDs who have personally led AI implementation and can challenge management on what it takes to move from experimentation to scaled adoption.
For marketplace boards, the questions are practical: Is internal adoption moving faster than the customer roadmap, and is that deliberate? Which AI products are live and creating measurable value? Which activities still need standalone functional ownership? And which parts of the customer and supplier journey does the marketplace ultimately need to own?
The direction is still a move from searchable databases towards decision engines, with more of the workflow and transaction around them. What our work over the past year has changed is our understanding of the route there: internal capability is moving ahead of customer-facing experience, supplier tools are often ahead of consumer products, and organisational boundaries are shifting before many of the end-state products have arrived.
If you would like to discuss how AI is changing your operating model, or are looking to add AI-native Executive or Non-Executive talent to your organisation, please contact hello@erevena.com or one of our marketplace specialists, Maria Josife, Jonnie Bryant, Holly Welstead and Jai Hooshmand.
FAQS
What are the challenges of implementing AI in organisational management?
In organisations struggling to drive real impact from AI, there is often an expectation that AI is the “job of the CTO”. In AI-forward organisations, adoption is driven from the CEO down.
While some organisations have appointed Chief AI Officers, mirroring the emergence of Chief Digital Officers during the early stages of digital transformation, the reality is that this is often a change role. In many organisations, the shift is instead being driven by a group of key executives: the CEO, CPeO (leading TOM redesign), CTO and CPO. Together, they are driving internal tooling, new external product capabilities and the iterative development of new revenue streams through lean, AI-led product cycles.
Every executive should have a view on how AI is disrupting their function.
Agility and the ability to operate with ambiguity are becoming must-have criteria for executives. There is no single answer or right approach, so the ability to think from first principles, create and chart a course is increasingly important for leaders operating through this period of change.
AI-forward thinking in the boardroom is becoming increasingly desirable. For executives not operating through this period of rapid change, maintaining genuine AI fluency can be difficult. More companies are therefore seeking Board members who are operating in AI-native or AI-forward environments, both to strengthen the Board’s understanding of risk and to support rapid adoption and value creation.
What are the latest trends in AI for marketplaces?
AI is further ahead inside marketplaces than in what customers see. In many businesses, internal adoption is moving faster than the consumer-facing product.
The clearest gains are in engineering, content, customer service, workflow automation and seller/supplier tooling.
Productivity gains are also easier to demonstrate than new revenue. Cost and efficiency benefits tend to show up faster than changes in pricing or broader commercial performance.
Marketplaces are starting to move from search towards understanding intent: not simply helping customers filter listings, but understanding what they are actually trying to achieve.
This makes first-party data and direct customer relationships increasingly important. Marketplaces need to be able to capture and act on that intent, particularly as AI assistants play a greater role in discovery and decision-making.
Agentic commerce remains early. Checkout.com found that only 3% of transactions currently involve AI agents, despite 89% of merchants preparing for it. Questions around identity, consent and liability are not yet part of mainstream discussion.
There is no single model for where AI should sit organisationally. Some businesses are centralising capability, while others are embedding it within existing functions or changing leadership structures altogether. What we see most consistently in organisations moving quickly is sponsorship from the CEO, with AI fluency increasingly expected across the senior leadership team.
Download a copy of this whitepaper here.


Get in touch with us
What are you looking to do?